Internet Anthropologist Think Tank

  • Search our BLOG


  • HOME
    Terrorist Names SEARCH:
    Loading

    Monday, November 10, 2008

    Are Federal Reserve screwing up?


    Are Federal Reserve screwing up?
    By Gerald: Internet Anthropologist Think Tank
    Nov  10,08


    I've already stated the Federal Reserve was incompentent.

    They have loaned out almost $2 trillion dollars.
    $2,000,000,000,000.00 to Banks.
    BANK HOLDING COMPANIES.

    And the banks still are not lending money, the banks don't really
    know what they have, as I understand it : Money Markets are not being 
    marked to the Market. Which is illegal, and counter-capitalism.
    And I assume the Fed is working 24/7 to get sub-prime paper and deratives out
    of the money markets.

    And the FED doesen't want to tell anyone to whom they loaned it, not Congress
    or the Press.

    Question is would disclosing the banks weaken confidence?
    Does not disclosing them weaken confidence?

    American Express just qualified as a bank holding company?
    So they qualify for a fed bail out, circumventing the Congress and
    using taxpayer money.

    And we have GM asking for a bailout.
    Clinton got the big 3 auto companies together and formed a partnership with the 
    Government to produce a family auto that got 80 miles to the Gallon.
    Correct me in comments if I'm wrong.

    Well the big 3 just played a game with Clinton.
    But the Japanese were not invited to the White house partnership.
    And were very scared, and dumped a lot of money into research.
    And came up with greatly improved gas milage,
    and the big 3 have been playing catch up ever since with
    the Japanese. And the market shares show this.
    I wouldn't mind a bailout for auto so much
    if they hadn't screwed up so big.

    Maybe GM will change to a bank holding co.?

    What ever, the tax payer needs to be getting a huge
    equity stake in all the corporations they bail out.
    And put into Social Security etc.
    Money back to the Tax payer, we are taking the risk.
    NOT paid back to the Government.
    It should be use to repay Government loans to the Social Security System,
    for example.

    If the taxpayer doesn't end up with a huge
    equity share in these corps then the tax payer 
    got SCREWED by Congress and the Lobbyiest AGAIN.

    Gerald
    Series 7 and 13

    .


    Labels: ,

    Terrorist Names SEARCH:
    Loading

    Wednesday, October 08, 2008

    Federal Reserve is protecting your Money


    WASHINGTON - MARCH 30:  Federal Reserve Chairm...Image by Getty Images via Daylife
      Federal Reserve is protecting your TAX bailout Money
      By Gerald: Internet Anthropologist Think Tank
      Oct. 8, 08


    AGI Insurance co. was in trouble and the Government ordered the Federal Reserve to bail them out to the tune of $85,000,000,000 ( 85 Billion dollars ).

    AGI was so happy they had a party, at a vacation spa with the money.
    Rooms were $1,600 a night, the total cost was $440,000 of taxpayers money.

    And the Federal Reserve was so angry they gave them $38,000,000,000 more.
    Thats $38 billion more dollars.
    Of course this time its a loan??? backed by HARD assets, of course the Federal
    Reserve hasn't told any body why they gave them more money, or what the first $85
    billion was spent on, besides the party, and haven't told any one what the hard assets are that back the other $38 billion.

    And the Federal Reserve has $700,000,000,000 ( $700 billion ) to buy bad loans.
    Mortages, right?? WRONG, credit card bad debt, bad auto loans etc.
    The banking lobbyists were working around the clock on this.
    Limited Golden parachutes, BULL.
    The new bail out gives the biggest banks, the biggest crooks , the ones charging 33% to 99%
    interest on credit cards, it gives them, the companies a GOLDEN parachute.

    We need new leadership at the federal reserve and 100% more transparancy.
    The CEOs only get performance bonuses, DUH, they just lined up $700 billion.
    Let the performance bonuses flow, flood the boardrooms, they just pulled off
    the biggest scam in history.

    This will go down in history as a new era of Bank Robber Barrons, and criminal banking activity.
    We have picked up noise back ground chatter about a lobbyist firms $100,000,000 ( $100 million dollar ) fee .

    And some congressmen's re-election chests are tuned to be truly over flowing, cascading, treasure CHESTS, in Gratitude from the Banking and Credit card criminal corporations.

    Whats the difference between a bribe and a political donation?
    The amount of money, a million dollar contribution, even broken up over time into smaller pieces, is a BRIBE.

    When did the Mafia usury interest rates of 30% or 99% become legal for banks and credit card companies?

    The Mafia was sent to prision for usury, but the banks don't get charged with usury they get the bankruptcy laws changed in the criminal banks favor.

    So the banks can pursue their vicitms of Usury to the grave, and collect their criminal proceeds.

    Why did they send the Mafia to prison but bail the banks out? LOBBYIST.

    THEY MADE A CRIME LEGAL. USURY.

    Gerald

    .

    A billion is a difficult number to visualize, let’s put a billion into perspective:
    A billion minutes ago, Jesus was alive.
    A billion hours ago, our ancestors were living in the Stone Age.

    How long would it take to count to one billion?
    If you count one number a second without stopping until you reach a billion. That task would take you 31 years, 259 days, 1 hours, 46 minutes, and 40 seconds.


    .


    Reblog this post [with Zemanta]

    Labels: , , , , ,

    Terrorist Names SEARCH:
    Loading

    Friday, May 02, 2008

    CREDIT CARD CO. :CRIMINALS helping terrorism

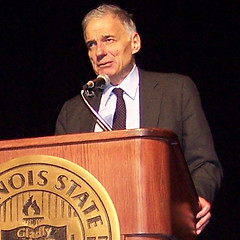
    Ralph Nader at ISU, April 14, 2008Image by guano via Flickr

    The Washington Post says federal regulators plan to announce new rules for the credit card industry.


    FED REGULATORS ARE IN CREDIT CARD INDUSTRY'S POCKET.

    THEY ARE TRYING TO USE BAND AIDS TO FIX ECONOMIC BEHEADINGS.

    THE CREDIT CARD INDUSTRY IS A THREAT TO THE GWOT,

    ID THEFT IS EPIDEMIC AND THE CREDIT CARD COMPANYS ARE MAKING MONEY OFF

    THE CRIME, CHARGES, FEES, INTEREST , AND CHARGES.

    THE CREDIT CARD COMPANIES HAVE INCORPORATED IN STATES WITH OUT ANY CONSUMER FRAUD LAWS.

    AND TERRORIST ARE FINANCING THE WAR WITH ID THEFT PROCEEDS.

    AND THEMSELVES ARE ENGAGING IN CRIMINAL ENTERPRISE WITH USURY CREDIT CARD CHARGES, SOME AS HIGH AS 97%.

    THE CREDIT CARD COMPANYS ARE THE NEW MAFIA. g

    "The proposed regulations, which could be finalized by year's end, would label as "unfair or deceptive" practices that consumers have long complained about," the paper says. "That includes charging interest on debt that has been repaid and assessing late fees when consumers are not given a reasonable amount of time to make a payment. When different interest rates apply to different balances on one card, companies would be prohibited from applying a payment first to the balance with the lowest rate."

    MORE:

    Feds seek to curb 'unfair, deceptive' charges for credit cards, overdrafts

    Federal regulators are moving ahead with new rules to stop "unfair and deceptive" practices involving credit cards and bank overdraft fees.

    The Federal Reserve approved the changes today, a day after the Office of Thrift Supervision and the National Credit Union Administration signed off. As USA TODAY's Kathy Chu explains, the proposal would:

    • Bar issuers from raising interest rates on existing debt, except under certain conditions, such as when a promotional rate expires or when a borrower pays 30 days or more late.
    • Prohibit issuers from calculating one month of finance charges based on two months' worth of activity, a punitive practice called double-cycle billing.
    • Require card issuers to apply monthly payments that exceed the required minimum at least partly to higher-rate card debt. Borrowers often face varying interest rates on credit card debt, for cash advances, balances transferred and purchases.
    • Prevent financial institutions from charging checking-account customers a fee for paying an overdraft — unless the customer has had the chance to opt out of this payment.

    Read the announcement and the full proposal (pdf) issued yesterday by the Office of Thrift Supervision.

    The public will have 75 days to comment, and the regulators expect the rule to be final by the end of the year.

    No immediate comment from the American Bankers Association, though ferocious opposition is likely to come.

    Here's more from the Wall Street Journal, The New York Times, Washington Post, CNNMoney and the Associated Press.

    Keep reading for more specifics.

    Read more...

    Labels: , , , , , , , , , ,